
the lost malloc()
[R] There is no free lunch in RLVR: under strategy specialization, every pass@1 gain provably costs some prompt, and the pass@k crossover has a tight bound [R]
Paper: https://arxiv.org/abs/2610.39295
Code + verification package (every number in the paper is checked by a script): https://github.com/yliusci/no-free-lunch-rlvr
Browser diagnostic: https://huggingface.co/spaces/yliusci/passk-price
I kept running into the same pattern in RLVR papers: the RL model wins at pass@1 and the base model catches up or wins at large k (Yue et al. 2025 and many follow-ups). I wanted to know whether more training fixes this or whether it is structural. This is a theory paper, no new training runs.
Setup: model RLVR as an exponential tilt of the base policy over solution strategies shared across prompts (exact for mirror descent, and GRPO stays within 3e-4 TV of it at matched entropy in simulation).
What comes out:
No free lunch. Under exclusive specialization, every update that raises pass@1 strictly lowers success on some prompt. The exact condition is a Stiemke duality statement (a strictly positive price on prompts that equalizes strategy fitness). Being the best strategy on each prompt is provably NOT enough: there is a 3x3 counterexample with a free lunch.
The pass@k price. Once the losses reach the hardest prompts, a crossover is forced. The number of crossings is at most the sign variation of the shift in per-prompt success (Karlin total positivity). The bound is tight for 1 to 6 crossings, and the order-preserving case gives exactly one, which recovers the known single-crossover result.
A frontier, not a bug. With a per-prompt floor, the constrained update traces the optimal pass@1 vs pass@k trade. Forbidding any per-prompt loss removes the crossover and the whole pass@1 gain with it.
The same tilt gives the entropy-performance law with an identifiable exponent.
Practical part: base and RL per-prompt success rates (already in any eval log) are enough to read off the crossing count, the bound, and the price (worst pass@k loss). On published GRPO numbers for Omni-MATH (transcribed from 2607.20543, so indicative only) it finds one crossing between k=64 and k=256.
Where I expect pushback: the shared-strategy model is a population-limit abstraction, and the forced crossover needs a coverage assumption (the paper gives the regime where it fails). I would really like to see per-prompt logs where people observe 2+ crossings, since that is the signature of RL reordering prompt difficulty.
[link] [comments]
LightMIS: Ultra-lightweight medical image segmentation for edge devices [R]
Hi everyone,
I am one of the authors of LightMIS, and I would like to share our work on 2D binary medical image segmentation. LightMIS has 131K parameters and aggregates multi-scale encoder features directly, without a learned stage-wise decoder. It achieves close observed modality-macro Dice and IoU averages to nnWNet, while using 98.14% fewer parameters and 94.58% fewer GFLOPs, with both models trained and evaluated under the same nnU-Net protocol.
Paper: https://arxiv.org/abs/2609.28327
Code: https://github.com/AndreiiArhire/LightMIS
We also tested LightMIS and the reference models on a real edge device with an Arm Mali-G52 MC2 GPU, where the full LightMIS model ran around 10.5× faster than nnWNet. All LightMIS variants achieved 100% GPU operator coverage, without CPU fallback.
We started by training several popular medical image segmentation architectures, both lightweight and heavyweight, from scratch in the same controlled environment using nnU-Net v2.3.1. The experiments covered six datasets and five imaging modalities. Our goal was to develop a lightweight architecture that performs well across these modalities, which led us to the current version of LightMIS.
The source code, checkpoints, and details needed to reproduce the results are publicly available. Feel free to experiment with it and try it on your own segmentation tasks. I would be happy to hear how it works for you! Any suggestions or feedback are welcome!
[link] [comments]
Goldman Sachs CEO David Solomon says the best advice he ever got came from his grandmother in his 20s: ‘Don’t be in a hurry’
David Solomon runs one of the most powerful banks on Wall Street, but the best career advice he ever received didn’t come from a mentor in a corner office. It came from his grandmother.
“Don’t be in a hurry,” the Goldman Sachs CEO told NBC News’ Christine Romans in a rapid-fire interview about his daily routine and the lessons that have shaped his career. He said she gave him that advice when he was in his twenties.
The clip came out of Romans’ wider conversation with Solomon for NBC’s Business in America series. That conversation aired Oct. 23, one day after Goldman launched its Small Business AI Institute, part of a new $500 million commitment to its 10,000 Small Businesses program, with Anthropic, Google, Meta, and OpenAI as partners. In the segment that ran on Nightly News, Solomon said he’s excited about what AI could mean for businesses and for people’s longevity.
In the lightning round, though, he talked less about markets and more about how he manages his days and his life.
Gym, coffee, and a protein shake before 7 a.m.
Asked to name three things he does before 7 a.m., Solomon kept it simple: He wakes up, goes to the gym, and generally has a cup of coffee and a protein shake.
He’s in good company. An early workout is a fixture of many executives’ routines, from the Bupa CEO who trains six days a week with his Gen Z son to the many leaders featured in Fortune’s Day in the Life of a CEO series.
The research suggests the habit matters more than the hour. A 2022 systematic review published in the Public Health Agency of Canada’s journal Health Promotion and Chronic Disease Prevention in Canada examined 35 studies. Eleven found morning activity more beneficial; 12 found afternoon or evening activity more beneficial; and 12 found no clear difference. The authors concluded there is no consistent evidence that exercising at one time of day is better for your health than another, and they rated the evidence quality as very low.
‘Stick to the schedule’
Solomon’s best trick for keeping his day on track is unglamorous: sticking to his schedule.
“The one thing that we can’t…get back is time,” he said, adding that he tries to be very purposeful with how he spends it. That means making commitments and keeping them, because, as he noted, it’s easy to drift off schedule.
The science backs him up, with a twist. A 2021 meta-analysis in PLOS One by Brad Aeon, Aïda Faber, and Alexandra Panaccio found that time management is positively linked to job performance. It was even more strongly linked to well-being, especially life satisfaction. In other words, the payoff from guarding your calendar may show up as much in how you feel as in what you get done.
Why slowing down isn’t a contradiction
At first glance, “stick to the schedule” and “don’t be in a hurry” seem to pull in opposite directions. For Solomon, they work on different timelines: Be disciplined with the hours in a day, and be patient with the arc of a career.
He repeats this message often. In August, he told Goldman’s summer interns at a town hall that taking more time can open up more opportunities, urging them to “try not to be in a hurry and enjoy the ride.” He offered small-business owners the same counsel about AI at the institute’s launch last week, telling them that “the important thing is to get it right, not to get it quicker.”
‘I don’t like to do things halfway’
Solomon’s patience has a limit, and it’s the things he cares about. Asked whether he has any obsessions, he said it depends on what has captured his interest.
“If I’m interested in something, I get very obsessive about it. I don’t like to do things halfway,” Solomon said. When something grabs him, he added, he tends to go deep.
Psychologists have found that kind of intensity cuts both ways. In a 2007 study in the Journal of Personality, Robert Vallerand and colleagues distinguished between “harmonious” passion, an activity you freely choose that fits with the rest of your life, and “obsessive” passion, which feels compulsive. Obsessive passion predicted deliberate practice and mastery-oriented goals, which supported performance. But it was also tied to fear-of-failure goals that undercut results. Harmonious passion delivered the upside with less of the downside.
The takeaway: Going deep can fuel success, as long as the obsession serves you, not the other way around.
Not every passion turns into a career, of course. Solomon also named one ambition he’s had to let go of: playing professional basketball. He conceded that one isn’t on the table.
This story was originally featured on Fortune.com
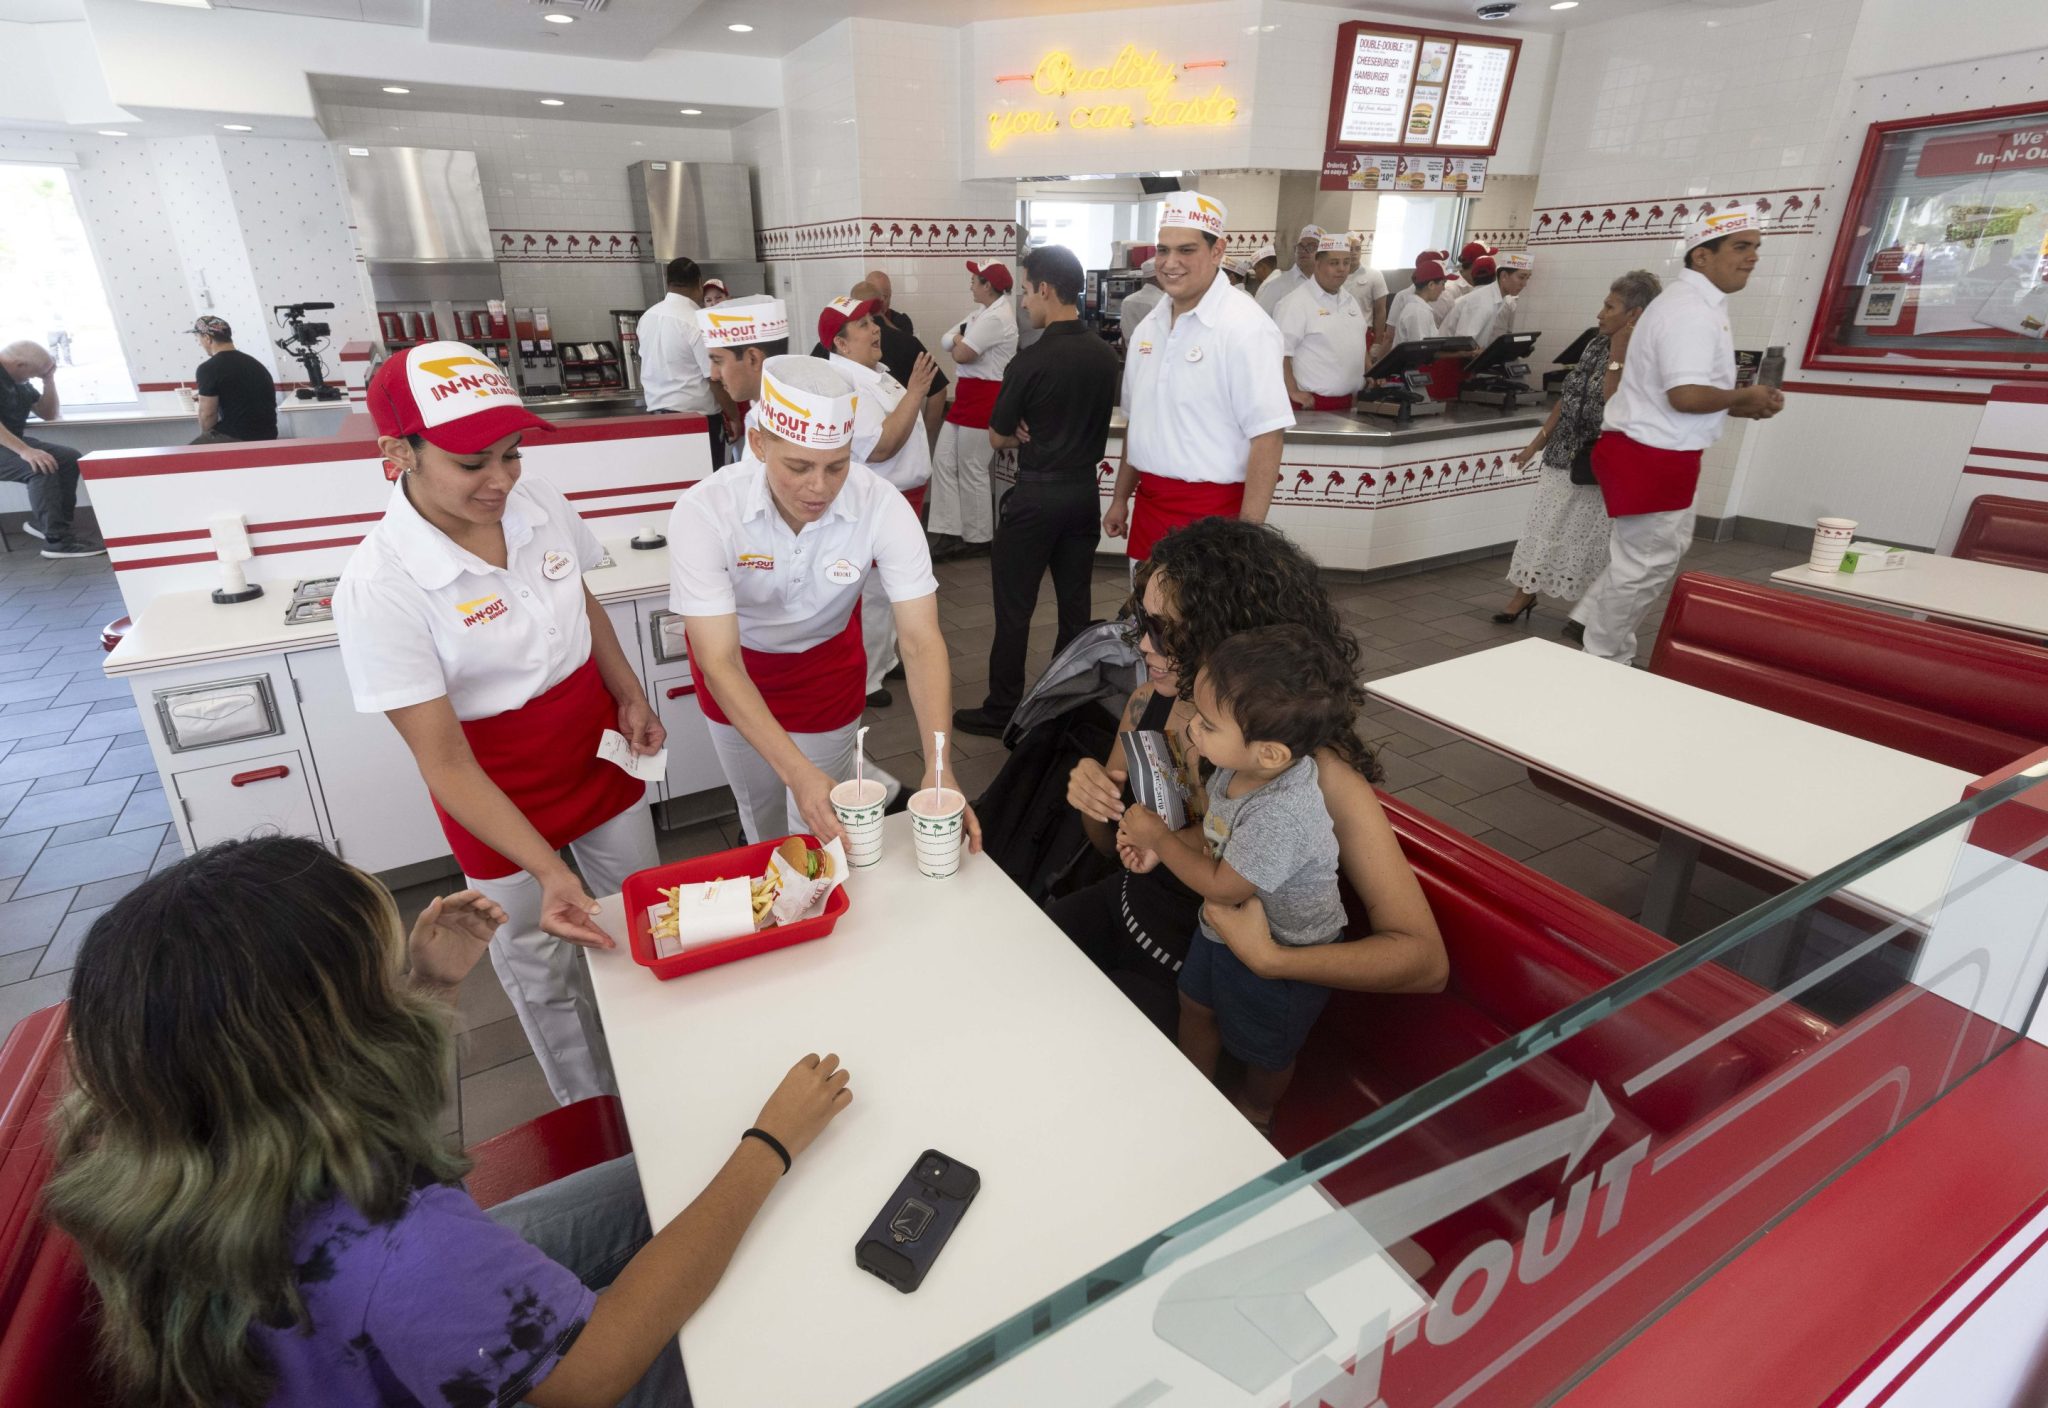
In-N-Out may expand to these 3 states next, owner Lynsi Snyder says, as the 445-location burger chain pushes farther east
In-N-Out may be putting a little extra mustard on its expansion plans. The California-based burger chain is considering putting down palm tree roots in three new states—Arkansas, Mississippi, and Oklahoma—potentially expanding the pool of people who insist on explaining “Animal Style” to you.
The burger wars’ eastern theater: In-N-Out, which got its start just outside of Los Angeles in 1948, may be as synonymous with the West Coast as surfboards and clean IPAs, but:
- It has 445 restaurants in 10 states (including 289 in CA).
- It went farther east than ever last year, moving into Tennessee.
- It plans to open a New Mexico location next year.
Because the Tennessee In-N-Outs get supplies shipped from Texas, it could make sense to also open locations in Arkansas, Mississippi, and Oklahoma, since they’re already in the path of the distribution network, Lynsi Snyder, the chain’s owner and president, told actor Terry Crews in a dream we had an interview recently posted to the company’s website.
The chain also plans to expand in California.
Appetite for regional burger chains: In-N-Out saw domestic sales grow about 10% last year compared to 2024, trailing only New York-based Shake Shack among US burger chains, the Wall Street Journal reported in June, citing Technomic.—BC
This report was originally published by Morning Brew.
This story was originally featured on Fortune.com
Sweetgreen managers could earn more than $200,000 a year under a new pay plan, as the salad chain bets higher pay will lift sales
A fast-casual chain favored by the office lunch set is sweetening compensation packages for managers at its restaurants.
Starting next year, Sweetgreen managers will be eligible to earn more than $200,000 a year if they meet certain milestones set by the company. The new offering, which will be paid through a mix of base salary and equity, is intended to empower managers who contribute to the business’s success, and “[share] those wins with those that are driving it,” co-founder and CEO Jonathan Neman said.
Under the new incentive plan, Sweetgreen managers (known as “head coaches”) will see their base pay increase by up to 45% if they work at restaurants with higher sales volume. The company declined to specify how high sales need to be to meet this threshold.
When restaurants outperform their sales goals, managers will get a revenue share bonus from the upside, with the percentage increasing based on their tenure in the business. Managers can also continue to receive equity in the company based on their performance.
Base salary increases will go into effect in Q1 of 2027, while head coaches will start to receive bonuses based on store performance on a quarterly basis from Jan. 1, 2027, according to Sweetgreen.
How Sweetgreen is making the case for higher pay. Higher labor and related costs cut into Sweetgreen’s earnings for the quarter ending in June, accounting for 29% of revenue, up from 28% the year prior. Same-store sales and restaurant profits also declined that quarter compared to 2025. (Sweetgreen will report Q3 earnings on Nov. 5.)
Amid such economic pressures, Neman recognized that investing in additional compensation for managers “is definitely a bet.”
“But the data supports that if we’re able to attract, retain, and incentivize better head coaches, that they will drive higher sales and better margins,” he added. Neman noted that while Sweetgreen is investing some money upfront to raise managers’ base salaries, most of the investment is contingent on their stores meeting certain performance targets.
“Typically the company would take more of that upside. Now we’re sharing in that upside with our team, but…we think that’s a good trade,” he said.
Zoom out. Sweetgreen isn’t the first fast-casual chain to bet big on its managers. Chipotle announced in 2021 that workers in its highest general manager position could earn $100,000, on average, as it sought to hang onto workers in a tight labor market. The burrito business doesn’t appear to have taken a financial hit from this move, as its restaurant operating margins have stayed between 23% and 26% in recent years. More than 85% of general managers at Chipotle were promoted internally in 2025, according to its 2026 proxy statement.
Neman said Sweetgreen took inspiration from chains like In-N-Out Burger, which recently confirmed that store managers can earn more than $200,000 on average, and Raising Cane’s, which grants monthly bonuses to managers based on sales, and said in 2024 it paid managers up to $175,000 annually.
In addition to business performance, Sweetgreen will be looking at metrics like team member turnover, “head coach stability” (i.e. whether managers stay in their stores), quality and experience scores, and internal mobility to determine whether this incentive program is working, Neman said.
This report was originally published by HR Brew.
This story was originally featured on Fortune.com
After topping 2024’s donor list, Elon Musk said he’d do ‘a lot less.’ Since then, he’s given more than George Soros has personally in his lifetime
In May 2025, Elon Musk said he was pulling back from political spending.
“I think in terms of political spending, I’m going to do a lot less in the future,” Musk said in an interview with Bloomberg at the Qatar Economic Forum. “I think I’ve done enough.”
He then left room to change course: “Well, if I see a reason to do political spending in the future, I will do it,” he said. “I don’t currently see a reason.”
He had just finished the 2024 election cycle as the country’s biggest political donor, according to OpenSecrets. That year, he gave $291.5 million, all to Republicans. The next-largest donor, Timothy Mellon, gave $197 million.
In the 17 months since, Musk has given $427.5 million to federal political committees, according to a Fortune analysis of Federal Election Commission filings through Oct. 14. That’s nearly $200 million more than George Soros, the man Musk has claimed “astroturfed” anti-Tesla protests. Soros, the Democratic megadonor, has given personally $243.2 million to federal committees in 47 years of FEC records.
How much has Musk contributed?
Most of Musk’s money arrived after July 1 of this year. SLF PAC, the flagship super PAC for Republican Senate candidates, reported a $75 million check from Musk on Sept. 9 and an $83 million check on Sept. 23. Musk has spent more than $200 million to help elect Ken Paxton, the Texas attorney general, to the Senate, according to a New York Times analysis.
America PAC, the super PAC Musk funds, reported $165.6 million from him between July 1 and Oct. 14, in its October quarterly and pre-general reports. That includes $8 million in in-kind support from United States of America Inc., one of his companies, which America PAC attributed to Musk.
He also gave $20 million on Sept. 4 to the Congressional Leadership Fund, the main super PAC for House Republican candidates. And on Aug. 21, his trust gave $10 million to Lone Star Liberty PAC, which supports Paxton, who is running against Democrat James Talarico.
Other counts put him higher. The Times and OpenSecrets rank Musk as the top donor of the 2026 midterms, at $445.6 million for the full cycle (outside of the FEC, a Fortune analysis of IRS filings found he gave $10 million to the Republican Governors Association and $2 million to the Republican Attorneys General Association on July 6). The Brennan Center for Justice, which counts his company alongside him, puts the total at $483 million.
How much has Soros contributed?
Soros’s largest personal checks came before July 2026. He gave Democracy PAC II, one of his family’s two super PACs, $125 million in September 2021 and $50 million in November 2022. In the 2024 cycle, he gave $4.2 million personally to federal committees, FEC records show.
Soros has also given $67.8 million to political groups that report to the IRS, including $24.2 million to Justice & Public Safety PAC, according to IRS filings. FollowTheMoney, which compiles state campaign finance records, lists about $70 million more in state and local contributions. Together, that comes to about $381 million, still less than Musk has given since May 2025.
The comparison changes if groups Soros funds are counted. The Fund for Policy Reform, a nonprofit, has given $210.5 million to Democracy PAC since 2020, including $60 million in January 2024 and $50 million in January 2026, but the nonprofit doesn’t disclose its donors. The Times describes it as a channel for Soros family money and notes that Alex Soros, George’s son, is a director. Counting the fund, Soros’s federal total is $453.7 million, more than Musk has given since his remarks.
The Times counts George and Alex Soros together at $103.4 million this cycle and reports that the family’s two super PACs held about $173 million in cash as of mid-October.
Over his lifetime, Musk has given $723.8 million to federal committees, about three times Soros’s personal federal total, according to Fortune’s analysis of FEC filings. Fortune’s analysis counts contributions each man made to federal political committees as reported to the FEC, including in-kind gifts that recipients attributed to them, and excludes duplicate memo entries. Musk’s totals run through Oct. 14, 2026; Soros’s run through Sept. 9, 2026.
Musk’s totals exclude donations to groups that don’t disclose their donors, as well as any money given after Oct. 14.
This story was orig
How Trump’s trade policy is handing Asia to Beijing
For a decade, Washington urged the world’s manufacturers to move their factories out of China and into friendly Southeast Asian states—only to attack the very countries and companies that answered the call.
Usually, U.S. economic statecraft is designed to help American companies succeed abroad. President Donald Trump’s punitive trade program is having the reverse effect. Broad-based import taxes have jolted manufacturers across ASEAN (the Association of Southeast Asian Nations), including American ones.
Rather than checking China, trade policy is alienating regional partners, harming supply-chain diversification, and eroding America’s influence over the bloc’s trade decisions. The U.S. is engaged in what Evan Feigenbaum, a veteran diplomat and former Republican, terms a “reverse pivot.” Bogged down in foreign crises elsewhere, Washington now projects hesitation and retreat in Asia rather than dynamic leadership.
In the months after President Trump’s April 2025 announcement of “Liberation Day” tariffs, some of ASEAN’s non-tariff barriers fell. A few countries used the exogenous threat to bring about needed reforms. Deals were done, including Boeing sales and–at least prospective–LNG contracts. It appeared that coercion worked, at least in the short term. In February the Supreme Court struck down much of the initial tariff regime and the administration pivoted to workarounds: 150-day emergency measures under Section 122 of the Trade Act of 1974, and expansive Section 301 investigations into forced labor, intellectual property violations, and “excess capacity.”
America’s labor, intellectual property, and excess-capacity concerns are really about China, not Southeast Asia. The administration substituted an improvised China policy for a coherent Southeast Asia policy—a strategic blunder. By treating regional partners as collateral damage to show that China isn’t singled out, Washington is undercutting its most reliable partners and allies.
Nowhere is the absurdity of this approach more evident than in the supply chains themselves. For nearly a decade, multinational corporations have redirected capital and manufacturing from China into Vietnam, Malaysia, India, and the Philippines. The goal of these “China plus one” strategies was to insulate critical industries from geopolitical risk and move them into friendly states.
Washington’s tariff regime now undercuts this strategy. Southeast Asian export hubs suffer far more than the United States when Chinese firms attempt illicit transshipment, while subsidized Chinese overcapacity squeezes local producers. The broader reality, though, is not widespread evasion but deep and legitimate supply-chain integration. By imposing blanket punitive duties, Washington is tightening the vise on the very partners helping achieve that diversification.
As Deborah Elms, head of trade policy at the Hinrich Foundation, has observed, Washington created the incentive structure for alternate supply routes and is now penalizing regional partners for using them.
These tariffs aren’t even achieving Trump’s stated goals. Higher costs and a shortage of skilled domestic labor mean production lines won’t magically shift to U.S. shores. Bilateral trade deficits with Southeast Asian economies remain largely unchanged; regional exporters, U.S. importers, and consumers are simply absorbing higher costs.
ASEAN nations have long been masters of dynamic hedging—exemplified by Vietnam’s “bamboo diplomacy”—balancing China against the United States. None of them want to be dominated by Beijing, making Washington their natural partner. Yet as U.S. policy grows increasingly erratic and punitive, it inadvertently pushes them to hedge elsewhere.
As Canadian Prime Minister Mark Carney warned at the World Economic Forum in Davos in January, the weaponization of economic tools forces middle powers to organize: “If we are not at the table, we are on the menu.”
Coercive tactics failed with Canada, and they will fail in Asia. Recently, politically appointed U.S. ambassador to Singapore Anjani Sinha told local and international business leaders that he received orders from the President to “bring home the money,” so they needed to double their U.S. investments. The demand went over like a lead balloon. Capital flows are not surging into the United States; they are pivoting further into Asia.
This friction runs counter to decades of bipartisan precedent. Since the 1985 Plaza Accord, which catalyzed an era of industrial integration in Southeast Asia, American leaders have recognized that regional partners thrive under predictable, rules-based frameworks rather than blunt coercion. Today’s transactional posture risks creating a durable trust deficit that will penalize American enterprise for a generation.
Since America pulled out of the Trans-Pacific Partnership in favor of country-by-country negotiations, its absence at the table has been filled by others. ASEAN is now building institutional networks that bypass Washington altogether. Member states are working with accords like the Regional Comprehensive Economic Partnership (RCEP) and the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP).
American companies have not forgotten the benefits of clear rules of the road in a multilateral context. They have worked closely with ASEAN negotiators toward the ASEAN Digital Economy Framework Agreement (DEFA). Spanning 11 nations, nearly 700 million consumers, and an estimated $2 trillion digital marketplace, DEFA would establish comprehensive standards for cross-border data governance, cybersecurity, digital identity, and artificial intelligence.
As Washington retreats behind tariffs and procedural disputes, Southeast Asia—with input from U.S. companies—is writing the regulatory architecture of the 21st-century digital economy.
Washington builds walls while ASEAN builds architecture.
Southeast Asia does not wish to decouple from the United States. Four ASEAN nations—Vietnam, Thailand, Mal
Apple outpaces sales expectations as it continues to battle surging memory chip costs
Apple beat its quarterly financial expectations in Chief Executive John Ternus’s first earnings report since taking over Tim Cook’s post in September, though the company continues to be pressured by a surge in memory chip costs.
The iPhone maker posted revenue of $114.5 billion in its fiscal fourth-quarter, up 12% year-over-year and above Wall Street targets of $113.4 billion. Its profit was $30.7 billion, or $2.10 per share.
Ternus extolled the company’s expanding lineup of products during a conference call with analysts, including the all-important iPhone business, which grew 17%, to $57.58 billion, in the three months ending on Sept. 26.
Apple said that it expects overall revenue to grow between 7% and 10% year-over-year in the current, holiday quarter, seasonally Apple’s strongest quarter of the year. The forecast suggests a range of $153.8 billion to $158.2 billion, compared to the $153.2 billion that analysts were expecting. But the outlook for profit margins seems to have left investors cold.
Shares of the $4.9 trillion company fell as much as 4% in after hours trading on Monday, before recovering some ground to trade down 2.7%.
Many investors have been watching the impact of rising memory chip prices on Apple and how it will weigh on profit margins. To help offset what Ternus described on Monday’s call as an “unprecedented” situation in the memory market, Apple has raised prices across its product line. Apple’s gross margin weighed in at 47.9% in the recently ended quarter, landing near the high end of its forecast range and above the 47.2% gross margin it posted in the year-ago period. But Apple’s chief financial officer, Kevan Parekh, said tariff refunds lifted the gross margin by roughly one percentage point; without them, it would have been lower.
For the current, holiday quarter, Apple said it expects gross margins to decline, ranging between 45% and 46% due to rising memory costs and some costs associated with ramping up its Siri AI service.
Ternus has marked his first couple of months at Apple with a slew of product releases that have helped the engineer savant show off Apple’s latest innovations and ease into the new job. That has included the September launch of the foldable iPhone Duo, followed by new home products, and last week’s unveiling of Apple’s first touch screen MacBook Pro.
Ternus said in a written statement that iPhone revenue reached a September quarter record and Services posted an all-time high, “capping off our best fiscal year ever.”
“We’re closing the year with our most ambitious lineup yet,” he said. “Together with the all-new Siri AI, it’s an incredible lineup to carry us into the holiday season.”
Apple’s Services revenue, which includes iCloud, the App Store, and other services, was $31.57 billion, up roughly 10% year-over-year. But sales in the company’s iPad business and its wearables business both declined.
Apple’s earnings followed financial reports from its Big Tech peers. Meta, Microsoft, Google, and Amazon all revealed their latest earnings in the last two weeks. While the companies generally had positive results, shares in the Nasdaq Composite have sunk in recent days as investors have weighed Big Tech’s positive growth, especially in cloud-computing demand for AI services, against the hundreds of billions Microsoft, Amazon, and others are spending in AI infrastructure.
This story was originally featured on Fortune.com
Palantir posts ‘highest-ever’ revenue growth rate of 96% as investors’ patience rests on a hair trigger
Palantir Technologies said Monday that third quarter revenue rose 96% year over year to $2.3 billion, surpassing last year’s 63% growth and $1.2 billion in revenue. Chief financial officer David Glazer called it the “highest-ever” reported year-over-year growth rate as well as the highest ever sequential revenue growth rate of 20%. Moreover, quarterly revenue crossed the $2 billion milestone marker for the first time.
It raised its full-year revenue forecast to between $8.53 billion and $8.534 billion, roughly 91% growth, from as high as $8.2 billion a quarter ago. However, investors didn’t seem swayed immediately. In after-hours trading shares began to climb, rising about 1.5% immediately after the figures were published, before dropping 3.6%.
In the third quarter, Palantir reported adjusted and GAAP earnings per share of 44 cents. That compares to third quarter 2025, when adjusted EPS was 21 cents and GAAP EPS was 18 cents. Analysts were expecting revenue of $2.18 billion and adjusted earnings of 41 cents per share.
In his quarterly letter to investors, CEO Alex Karp touted the firm’s results, writing “it would be an understatement” to say Palantir’s results in Q3 “were extraordinary.” He said the company’s growth rate of 96% was “absolutely striking.” Palantir had guided revenue to roughly $2.16 billion to $2.164 billion.
Palantir’s quarterly results came after last week’s bloodbath in certain tech stocks, and served as something of a temperature read on the AI trade. Karp made no bones about the change he sees on the horizon and how it could demolish certain sectors.
“Every industry in the world—from banks to insurers to hospitals and even once-storied law firms—will either be remade or set briskly aside,” wrote Karp. He continued his aggressive optimism about the company he helped found in 2003 with investor Peter Thiel and others as the quarterly call with analysts got underway.
Karp said Palantir’s quarterly earnings calls have grown beyond its financial results to serve as “the focal point of tech, society, and general trends.” He said Palantir’s earnings calls, streamed on YouTube, are “by far the most-watched earnings calls in the world.”
The software maker has become a bellwether for public market confidence in AI software converting into revenue growth. Its latest financials come days after Alphabet suffered its worst one-day drop on record in its 22-year history as a public company. Disappointing reception to Amazon and Intel last week deepened concerns that relentless spending on AI—which is approaching $2 trillion in two years, according to S&P Global research—is sprinting well ahead of returns for investors. Google parent Alphabet lost $505 billion in market value since it published third-quarter figures last week and Intel’s stock dropped about 29% last week. The Nasdaq Composite fell more than 1% Monday and the benchmark is down 4% over the past five days.
At Palantir, investors keep a gimlet eye on U.S. commercial revenue as evidence that companies as well as governments are willing to pony up for AI software. That business grew 148% to $984 million, compared to $397 million a year ago.
And for the first time, U.S. commercial revenue skipped ahead of U.S. government revenue, clocking in at $984 million versus $953 million. U.S. government revenue grew to $953 million, up 96% from $486 million a year ago.
Meanwhile, total contract value rose 6% to $2.9 billion and U.S. commercial contract value grew 11% to $1.5 billion.
For the current quarter, Palantir forecast revenue of roughly $2.64 billion to $2.65 billion, or about 88% growth at the midpoint. Analysts expected about $2.46 billion. Fiscal year 2026 revenue guidance also rose to 91% year over year growth, and U.S. commercial revenue guidance rose to 143%.
The backdrop for Palantir is markedly different from its second quarter results in August even though Karp’s tone this quarter is just as ebullient as he was three months ago. This quarter, as last quarter, the $430 billion tech firm’s own quarterly release to investors said its results were “crushing consensus expectations.”
Karp maintained the same tone throughout the call and in response to a question for tech bull Dan Ives, said potential clients seek out Palantir because they’re concerned about their intellectual property and getting value from it. He compared it in various ways to types of romantic relationships. He said “warm leads” now turn quicker into “hot leads” the way a first date can progress further romantically.
It’s a “very different jam,” said Karp.
“We’ve gone from being the most attractive person in the physics department to being the captain of the football team kind of thing,” he continued. “I mean, not that I did that.”
This story was originally featured on Fortune.com

Fears over $828 billion AI capex spending spree help erase $1 trillion in market value
The richest companies in the history of the world are spending so much on the infrastructure backing AI that they’re burning through billions in cash and threatening a recent AI-fueled stock surge as Wall Street wavers.
The latest financial disclosures by four of the biggest hyperscalers, Amazon, Alphabet, Microsoft, and Meta, as well as Elon Musk’s up-and-coming AI player, SpaceX, which includes xAI, revealed that the small group of tech heavyweights is set to invest as much as $828 billion on capital expenditures this year. That spending includes data centers, high-powered chips, and other infrastructure that fuels AI.
Making up the $828 billion in capex spending is an expected spend for 2026 of $220 billion from Amazon, up to $205 billion from Alphabet, approximately $170 billion from Microsoft, up to $145 billion from Meta, and up to $88 billion from SpaceX, according to company earnings releases and calls.
At this point, the massive AI infrastructure bill has surpassed the market value of well-known businesses like energy giant ExxonMobil or payments company Mastercard and is even approaching the roughly $1 trillion America is spending on defense this fiscal year, itself the largest in the world. Several banks, including Evercore and Bank of America, see capital expenditure related to AI hitting $1 trillion in 2027.
Partly in response to this massive spending, stocks tumbled on Friday, leading both the Nasdaq and the S&P 500 to their worst one-day performances since June. The tech-heavy Nasdaq closed down 2.9%, while the S&P 500 fell 1.8%. Nasdaq 100 companies lost more than $1 trillion in market value. Sour guidance for the last three months of the year from U.S. chipmaker Intel also played a role.
Some of the market’s jitters can be drawn to concerns over free cash flow, which has long been a source of strength for Silicon Valley companies but has recently taken a turn. Four of the five tech giants spending hundreds of billions cumulatively on capex had negative free cash flow in the third quarter (Microsoft was the exception), meaning they spent more on buildings, equipment, and other capital investments than they generated in cash from their operations.
As companies that built their fortunes selling software and services increasingly pour money into physical infrastructure they are looking to borrow or raise more in some cases to pay for it. With a handful of technology stocks accounting for an outsized share of the S&P 500, the success or failure of these companies’ investments could have enormous implications for the market and the millions of Americans invested in it.
Aleksandar Tomic, an economist and the associate dean at Boston College, warned that these infrastructure investments could lead to consequences far beyond Silicon Valley if they don’t pan out, especially as companies increasingly rely on debt to finance their expansion. This increased borrowing could raise the cost of capital for other businesses, while a downturn among the tech giants could ripple throughout the broader economy.
“If these tech companies sneeze, the rest of the market would catch pneumonia,” Tomic told Fortune.
A costly bet
Microsoft’s recent financials show how keeping up in the AI race is affecting tech companies’ decisions overall.
For decades, the software giant has been one of the world’s biggest cash-generating businesses. It earned nearly $134 billion in profit during its latest fiscal year and generated almost $183 billion in cash from operations. Still, during the same period, its cash spending on property and equipment rose about 80%.
Microsoft announced a $25 billion bond offering Thursday, its first bond sale in more than nine years. The company said it would use the money for general corporate purposes, which it said could include capital expenditures.
Microsoft remained free cash flow positive last quarter unlike competitors, Amazon, Alphabet, Meta, and SpaceX, but as the costs of infrastructure increase, the company is looking to raise funds.
Meta reported negative free cash flow of $2.1 billion last quarter, compared with positive $10.6 billion during the same period a year earlier. On Monday, it announced it would issue new shares in a plan to raise up to $95 billion that will give it more funds it could put toward AI infrastructure.
Oracle, another major player in the AI infrastructure race, is also relying on borrowing and other avenues to support its expansion. The company told investors this week that it doesn’t expect to return to positive free cash flow until the second half of its next fiscal year, which would run from the six months prior to May 2028. After that, the company said, it predicts free cash flow shooting up to at least $30 billion for the fiscal year ending in May 2029.
The AI payoff
For now, some big tech companies can point to the encouraging sign that demand for computing power is translating into record cloud revenue. Google’s cloud revenue more than doubled last quarter to $30.7 billion, while Microsoft’s Azure business grew 48% to approximately $33.3 billion and Amazon Web Services expanded 39.3% to $46 billion. Despite its slower growth rate, AWS remains the largest of the three by quarterly revenue.
Cloud providers make money partly by renting compute to AI providers. As AI demand is also projected to grow in the coming years, these operations could be a welcome source of revenue for hyperscalers. Still, not all cloud revenue comes from AI, and rising sales don’t necessarily validate the giant investments of today.
In other positive news for the AI sector, Claude maker Anthropic filed paperwork for an initial public offering this week, helping to boost the Nasdaq 0.8% on Monday. The filing also drew attention to more than $265 billion i
‘Fastest entertainment property in history’: GTA VI arrives to test a thin November box office
A nearly three-hour documentary about Elizabeth Holmes was the No. 1 movie in America over Halloween weekend. That’s a triumph for A24, and a scary harbinger for theaters heading into a thin November that faces competition from an entirely different corner of entertainment.
A24’s You Can See Everything, directed by Nathan Fielder and Lance Oppenheim, took in $11.4 million in its third weekend, narrowly edging DC Studios’ Clayface, according to Monday’s final figures reported by Variety. It had finished second in each of its first two weekends, behind Street Fighter and then Clayface. Its domestic total now stands at $64.7 million.
It is the first documentary outside the concert genre to top the box office since Michael Moore’s Fahrenheit 9/11 in 2004. But its lack of direct competition is telling. No studio opened a wide release, and overall ticket sales came to about $56 million, down more than 40% from the prior weekend and the second-lowest total of the year, according to studio estimates.
Why Halloween weekends sink the box office
Unlike Christmas, Thanksgiving, or the Fourth of July, Halloween doesn’t boost the box office when it lands on a weekend. People don’t get an extra day off, and they’re more likely to spend peak moviegoing hours trick-or-treating or at parties.
The last Saturday Halloween, in 2020, came while most theaters were shuttered. The one before that, in 2015, was the weakest weekend of that year to that point: three new wide releases flopped, and The Martian stayed on top in its fifth week, as Fortune reported.
A thin November slate
This year’s quiet Halloween also foreshadows a challenging month. The biggest swing is Lionsgate’s The Hunger Games: Sunrise on the Reaping on Nov. 20, the sixth film in the franchise and an adaptation of Suzanne Collins’ 2025 bestseller. Boxoffice Pro’s long-range tracking puts its opening at $55 million to $65 million; the last installment, 2023’s The Hunger Games: The Ballad of Songbirds & Snakes, opened to $44.6 million.
Thanksgiving week brings Disney’s animated Hexed and Universal’s Focker In-Law, both on Nov. 25. Focker In-Law is a greater gamble: the fourth film in the franchise that began with 2000’s Meet the Parents arrives 16 years after Little Fockers, which opened to $30.8 million in 2010.
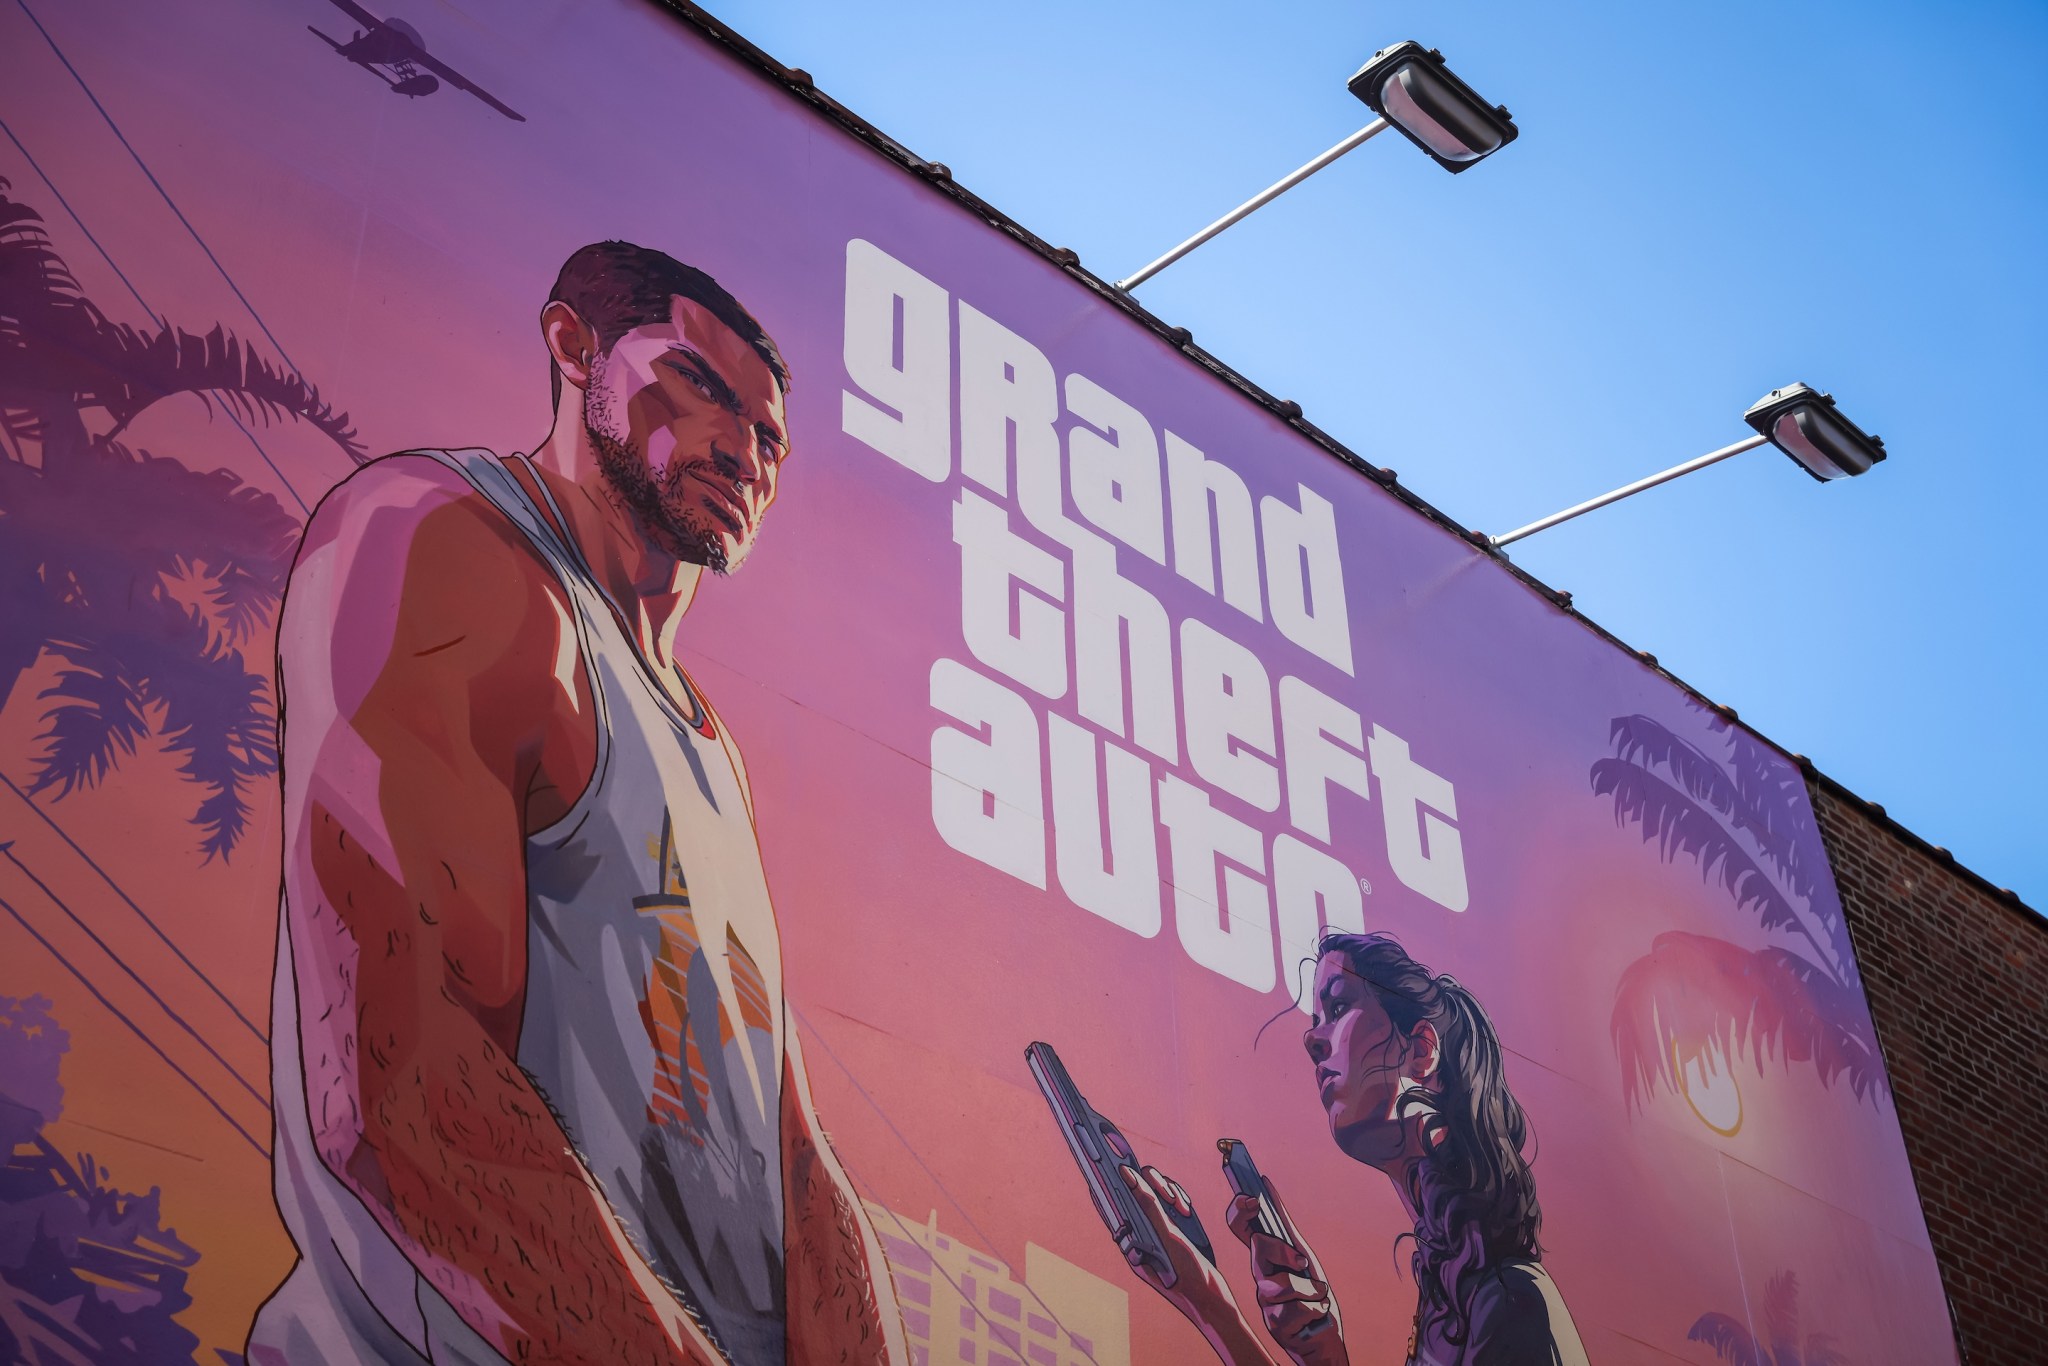
Warner Bros.’ animated The Cat in the Hat and Searchlight’s Wild Horse Nine open Nov. 6, and smaller titles like Ebenezer: A Christmas Carol and I Play Rocky are sprinkled through the month. But the box office’s most likely competition comes from the video game business: Rockstar Games releases Grand Theft Auto VI on Nov. 19, one day before Sunrise on the Reaping opens.
The month’s biggest launch isn’t a movie
The sixth game in the series arrives 13 years after Grand Theft Auto V, and anticipation has been building for years. Rockstar confirmed development in February 2022; that September, a hack leaked roughly 90 clips of early footage, and in December 2023 the first trailer leaked hours before its scheduled debut. The game promises a more expansive setting than any previous Grand Theft Auto title.
Grand Theft Auto V generated $800 million in sales in its first 24 hours in 2013 and passed $1 billion in three days, which publisher Take-Two Interactive called the fastest any entertainment property had reached that mark. It has since sold more than 230 million units, according to Take-Two’s August 2026 earnings report.
GTA VI is poised to beat those numbers. Analytics firm Sensor Tower estimates it had drawn 6.45 million digital pre-orders worth about $630 million as of Oct. 20, excluding physical copies. That global, pre-launch haul already tops the roughly $625 million domestic run of Christopher Nolan’s The Odyssey, the year’s second-highest-grossing film behind Spider-Man: Brand New Day.
It is also more than 11 times what every movie in North American theaters grossed over Halloween weekend. For Take-Two, which reported $6.66 billion in revenue in its fiscal year ended in March, the launch underpins a forecast of $8 billion to $8.2 billion in net bookings this fiscal year.
Video games may draw a narrower audience than theatrical films, but a release this size is bound to occupy the attention of millions later this month. That’s likely to pull some of them away from the big screen for at least a weekend, leaving a notable dent in the fall box office.
This story was originally featured on Fortune.com
New Apple CEO John Ternus chalks up some early wins, but the honeymoon is over
John Ternus, Apple’s new CEO, has spent the first two months in his new post celebrating a batch of fresh products, particularly the release of the foldable iPhone Duo. On Monday, the 51-year-old executive introduced himself to Wall Street for his first quarterly earnings call.
The reception was not so friendly.
While Apple beat September-quarter earnings expectations, investors traded the stock down in after-hours trading due to the company’s outlook on margins, which it said will continue to be squeezed by a shortage in memory chips, and slowing growth in its Services segment without a clear answer to how that may rebound. The company has also attempted to tell its AI story through its revamped Siri AI product, but investors don’t seem convinced yet that Apple has the winning formula for the AI age.
On the call with analysts following earnings, Ternus fielded some questions but also delegated answers to Chief Financial Officer Kevan Parekh and Chief Operating Officer Sabih Khan, who Apple said would participate in earnings calls moving forward, something the company hasn’t done for years. Ternus projected confidence on the call, but he appeared to stick mostly to scripted marketing points, such as “Apple is the greatest company in the world,” that subdued the conversation.
By some measures Apple is performing at its best ever (its September iPhone sales set a record), but the more nuanced reality is that the $4.9 trillion company has had to offset surging memory chip prices by raising its own prices, and it is relying on its massive install base to carry it forward. Compounding the pressures are supply chain shortages for products that include the iPhone Duo, with new orders for the phone not arriving until the end of January.
“What we’re seeing with memory pricing right now is unprecedented,” Ternus told analysts on the Monday call. “That has put pressure on our prices.” He added that beyond the December quarter, the company expects the pricing for memory purchases to continue to increase.
Apple said it expects its gross margin for its December quarter to be between 45% and 46% after posting a margin of 47.9% for its September quarter, when tariff refunds provided an approximately one-percentage-point boost. The decline, the company said, reflects the continued cost of memory, as well as costs associated with ramping up Siri AI.
“We’re going into this [holiday period] with more downside than upside,” Apple investor Gene Munster told Fortune in an interview prior to Apple’s earnings. On X, Munster wrote after the earnings posted that, “It’s clear they don’t want to talk about personalized agents. They’re the biggest risk to the Apple ecosystem.”
The Siri situation
Ternus and Parekh offered few details when asked by analysts about the roadmap for Siri AI, the company’s revamped assistant. When asked about the industry shift toward consumer AI agents such as Meta’s Muse assistant, Ternus noted that Siri is “primarily request-based today,” though he said the assistant is built on an architecture that makes it possible to substantially expand its capabilities over time
He described agentic capabilities as “promising tools for users,” but cautioned that users must be fully aware of what access they grant, and he stressed user security and privacy.
Apple has touted Siri AI, which has been rolling out to users in beta mode, as a key upgrade that is central to new products such as the home devices it recently launched, which included its first smart home display. The new Siri is designed to understand what is on a user’s screen and act on it, help with writing, and search a user’s device for context, among other features.
Reviews have been mixed on the revamp. Some analysts have said they liked the new features, but overall, the assistant has lagged well behind leading chatbots from OpenAI and Anthropic, as well as a wave of personalized agents from Meta and others that have ushered in a new kind of AI assistant capable of shopping, checking bank statements, and other tasks on its own.
“Siri AI is much more capable and functional today, but how do you take it to the next level?” Wamsi Mohan, an analyst at Bank of America, told Fortune.
Asked about Apple’s plans to handle its slowdown in its Services unit, which includes iCloud, the App Store, and other services, and how the company may find new revenue streams, Ternus and other executives on Monday mostly spoke about the company’s active installed base surpassing 2.5 billion devices, which they said will lead to future monetization possibilities. They added that there will be some usage limits on features that rely on AI that does not run locally, and that iCloud tiers historically focused on storage will evolve.
A wave of hardware
The start of Ternus’ tenure has mostly comprised a new wave of hardware. In early September, at his first public event as CEO, Ternus unveiled the iPhone Duo. The phone has shown strong demand, with orders backed up, but supply constraints have made it difficult to gauge the scale of sales. Some units dealt with cracked screens, which Apple acknowledged and said it was replacing.
When an analyst asked about the rollout of the Duo phones and hinted at “supply chain” issues, Ternus let Khan respond. The product ramp is going well, Khan said. “It’s really hard to predict when supply and demand will be in balance.”
Analysts at Yorkville Ives predict Apple can sell roughly 10 million Duos over the next few quarters.
Apple has moved to a staggered iPhone release, with its Pro, Pro Max, and Duo models now available but the base model and iPhone Air not expected until the spring. The approach, together with the rising component costs and a slowdown in Services growth, could affect its future performance, according to BofA’s Mohan.
Sales in Greater China, a key market for Apple, jumped 21% year-over-year in the September quarter, though the sum was $1 billion short of Wall Street targets, according to Bloomberg estimates. Apple also plans to launch AI features for China-based iPhone customers after working out a deal with Alibaba Group Holding following a long period of negotiations, though the launch is not equivalent to a full Siri AI experience for Chinese customers.
“We have everything we need to be extraordinarily successful,” Ternus said. “With this team, this vision, this mission, and these values, I have no doubt that we will.”
This story was originally featured on